Introduction
A bank reports a strong capital adequacy ratio. Its regulatory disclosures indicate that it comfortably exceeds minimum capital requirements. Its balance sheet contains substantial assets, and its management describes the institution as financially sound.
Yet within days, depositors begin withdrawing funds, market confidence deteriorates and the bank faces an existential crisis.
How can a bank that appears adequately capitalized experience such severe financial distress?
The answer lies in one of the most important distinctions in banking: capital adequacy and liquidity are not the same thing.
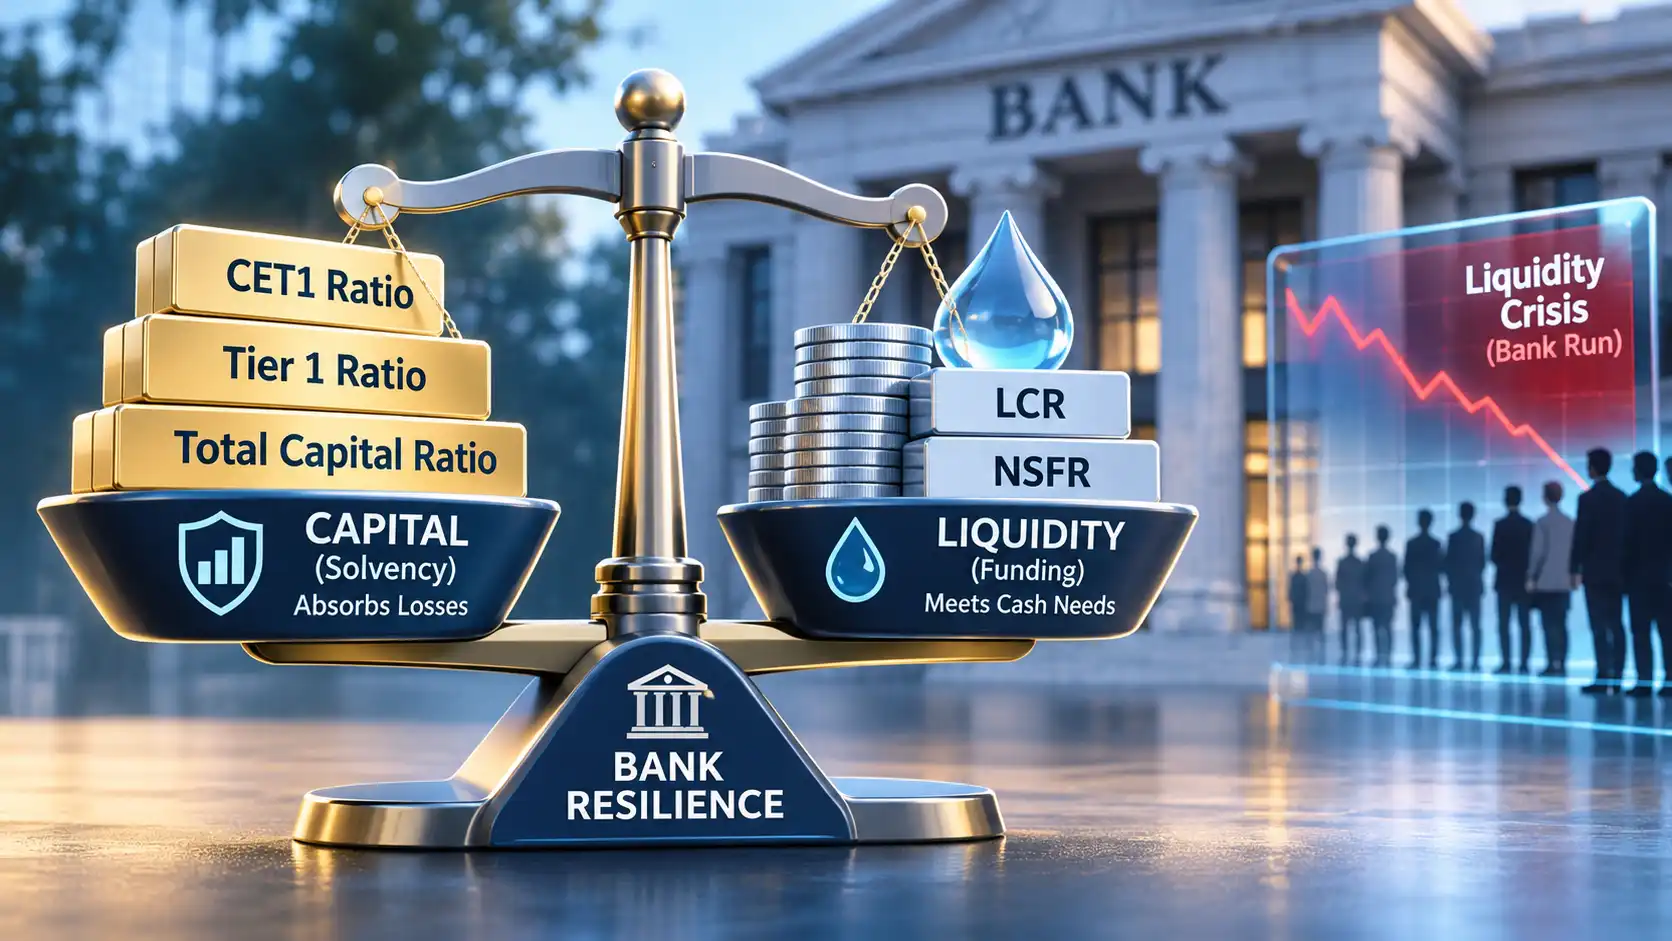
Capital represents a bank's capacity to absorb financial losses. Liquidity represents its ability to meet payment obligations when they become due.
Both are essential, but they address different risks.
A bank may hold sufficient regulatory capital while lacking the immediately available cash or reliable funding needed to satisfy a sudden surge in withdrawals.
Conversely, an institution may have ample liquid assets while suffering losses so large that its capital becomes insufficient.
The international banking turmoil of 2023 brought this distinction into sharp focus.
The failures of Silicon Valley Bank and First Republic Bank in the United States, alongside the crisis involving Credit Suisse in Switzerland, demonstrated how interest rate exposure, funding concentration, confidence and liquidity pressures can interact with broader weaknesses.
These events challenged the assumption that compliance with headline financial ratios is sufficient evidence of institutional resilience.
For banking professionals, investors and policymakers, understanding the relationship between capital and liquidity is essential to assessing the stability of financial institutions.
1. The Fundamental Difference Between Solvency and Liquidity
Solvency and liquidity are related but distinct concepts.
A bank is economically solvent when the value of its assets exceeds its liabilities, leaving a positive residual value for owners.
Liquidity concerns whether the bank can obtain enough usable cash to fulfill obligations as they fall due.
A simplified comparison illustrates the distinction.
| Characteristic | Solvency | Liquidity |
|---|---|---|
| Central Question | Are assets sufficient to cover liabilities? | Can obligations be paid when due? |
| Main Concern | Loss absorption and financial viability | Cash availability and funding continuity |
| Key Resources | Equity and qualifying regulatory capital | Cash, reserves, liquid securities and funding access |
| Typical Risks | Credit losses, asset impairment and valuation declines | Deposit withdrawals, refinancing pressures and collateral calls |
| Regulatory Measures | CET1, Tier 1 and Total Capital Ratios | LCR and NSFR |
| Time Horizon | Financial resilience and loss absorption | Immediate, short-term and structural funding needs |
Consider a bank that owns $100 billion in assets and owes $90 billion to depositors and other creditors.
Its simplified accounting equity is $10 billion.
However, suppose depositors suddenly demand $20 billion in withdrawals.
The bank may have only $5 billion in immediately available cash.
Although the balance sheet shows positive equity, the bank cannot meet the withdrawals using cash alone.
It must raise additional liquidity by selling assets, borrowing or obtaining eligible central bank financing.
If those options are unavailable, insufficient or too slow, the institution can face a liquidity crisis.
Importantly, accounting equity is not identical to regulatory CET1 capital, and neither is necessarily equivalent to economic net worth measured using current market values.
This distinction becomes especially important when assets contain substantial unrealized losses.
2. What Are Bank Capital Ratios?
Capital ratios assess the financial resources a bank has available to absorb certain losses relative to its risk exposures.
Under the Basel III framework, regulatory capital is divided into categories reflecting the quality and loss-absorbing characteristics of different instruments.
The most important measures are Common Equity Tier 1, Tier 1 and Total Capital.
Common Equity Tier 1 (CET1) Ratio
CET1 is the highest-quality category of regulatory capital.
It consists primarily of eligible common equity and retained earnings after applicable regulatory adjustments.
The CET1 ratio measures this capital relative to the bank's risk-weighted assets.
CET1 Ratio = (CET1 Capital ÷ Risk-Weighted Assets) × 100
Consider a hypothetical bank with:
- CET1 capital: $12 billion
- Risk-weighted assets: $100 billion
Its CET1 ratio is 12%.
This indicates that the bank has $12 of CET1 capital for every $100 of risk-weighted assets.
It does not mean the bank holds $12 in cash for every $100 in deposits or loans.
Tier 1 Capital Ratio
Tier 1 capital consists of CET1 and qualifying Additional Tier 1 instruments.
The Tier 1 capital ratio is calculated by dividing Tier 1 capital by risk-weighted assets.
Additional Tier 1 instruments are designed to absorb losses under specified conditions, but their contractual features and regulatory treatment can differ from ordinary common equity.
Total Capital Ratio
Total regulatory capital includes Tier 1 and eligible Tier 2 capital.
Tier 2 capital generally provides additional loss-absorbing capacity, particularly in resolution or failure, subject to applicable regulatory rules.
Total Capital Ratio = (Tier 1 Capital + Tier 2 Capital) ÷ Risk-Weighted Assets × 100
These ratios measure capital adequacy, but they do not directly measure the ability to fund immediate withdrawals.
3. Basel III Capital Requirements Explained
The Basel III framework establishes internationally agreed minimum capital standards.
The core risk-based minimums are:
| Capital Measure | Basel Minimum | Minimum Plus 2.5% Conservation Buffer |
|---|---|---|
| CET1 Capital Ratio | 4.5% | 7.0% |
| Tier 1 Capital Ratio | 6.0% | 8.5% |
| Total Capital Ratio | 8.0% | 10.5% |
The capital conservation buffer must be met with CET1 capital.
Additional requirements can apply, including countercyclical capital buffers, systemic importance surcharges and other jurisdiction-specific or bank-specific requirements.
The figures should therefore not be interpreted as universal final requirements for every bank.
Banks may also be subject to a leverage ratio that assesses Tier 1 capital relative to a broader exposure measure rather than risk-weighted assets.
Why Risk-Weighted Assets Matter
Regulatory capital ratios use risk-weighted assets rather than total assets.
Different financial exposures receive different risk weights based on applicable regulatory methodologies.
For example, certain government securities may receive lower credit risk weights than unsecured corporate loans.
However, a low credit risk weight does not necessarily mean an asset is free from interest rate risk, market value fluctuations or liquidity constraints.
A bank can therefore report a strong risk-weighted capital ratio while holding assets that may decline substantially in market value when interest rates rise.
This illustrates an important limitation.
Capital ratios depend not only on the amount of capital available but also on how financial risks are measured.
4. Why Capital Cannot Be Used Like Cash
One of the most common misconceptions in banking is that capital represents a pool of money immediately available to repay depositors.
In reality, regulatory capital is a measure of financial loss-absorbing resources, not a separate cash reserve.
When shareholders contribute capital to a bank, the resulting funds may be used to finance loans, purchase securities or support other activities.
The bank's capital remains reflected in its financial structure, but the original cash may have been transformed into other assets.
Consider a bank holding $10 billion in regulatory capital.
That does not mean it has $10 billion in immediately withdrawable cash.
The institution may have invested a significant portion of its funding in loans or long-term securities.
Capital is essential because it absorbs losses and protects creditors.
However, meeting an unexpected withdrawal requires cash or assets and funding arrangements that can be converted into cash when needed.
A liquidity crisis therefore cannot necessarily be resolved merely by pointing to a strong capital ratio.
5. Understanding the Liquidity Coverage Ratio (LCR)
The Liquidity Coverage Ratio is a central component of Basel III's liquidity framework.
Its objective is to promote short-term resilience by requiring covered banks to maintain sufficient high-quality liquid assets to withstand a prescribed 30-day stress scenario.
LCR = (Stock of High-Quality Liquid Assets ÷ Total Net Cash Outflows Over 30 Days) × 100
Under the Basel standard, the normal minimum requirement is 100%.
This means that a bank should hold eligible high-quality liquid assets at least equal to its modeled net cash outflows over the stress period.
What Are High-Quality Liquid Assets?
High-quality liquid assets, or HQLA, are assets expected to be readily convertible into cash with limited loss of value under prescribed stressed conditions.
Depending on regulatory classification, they may include central bank reserves, qualifying sovereign securities and other eligible liquid assets.
Not every investment held by a bank qualifies as HQLA.
Eligibility is subject to regulatory criteria, valuation adjustments, concentration limits and operational requirements.
Illustrative LCR Calculation
Suppose a bank reports:
| Indicator | Amount |
|---|---|
| Eligible high-quality liquid assets | $30 billion |
| Modeled 30-day net cash outflows | $25 billion |
| Liquidity Coverage Ratio | 120% |
The bank holds $1.20 in eligible liquid assets for every $1 of modeled stressed net cash outflows.
Its LCR exceeds the Basel minimum.
However, this does not guarantee that the bank can survive every conceivable liquidity shock.
A real bank run may involve withdrawals that are faster or larger than those assumed in the regulatory model.
Liquidity may also be held in the wrong currency, at the wrong legal entity or in assets that cannot be monetized quickly enough.
Furthermore, Basel's LCR framework expressly allows banks to use their HQLA buffers during genuine stress, even if doing so temporarily reduces the ratio below 100%.
The LCR is therefore a regulatory resilience tool, not an absolute guarantee against failure.
6. The Net Stable Funding Ratio (NSFR)
While the LCR focuses on short-term liquidity stress, the Net Stable Funding Ratio addresses the stability of a bank's funding structure over a longer horizon.
The NSFR encourages banks to maintain funding that is sufficiently stable relative to the liquidity characteristics and maturities of their assets and off-balance-sheet exposures.
NSFR = (Available Stable Funding ÷ Required Stable Funding) × 100
The Basel standard generally requires an NSFR of at least 100%.
Consider a hypothetical institution with:
| Indicator | Amount |
|---|---|
| Available stable funding | $90 billion |
| Required stable funding | $80 billion |
| Net Stable Funding Ratio | 112.5% |
The institution meets the standard in this simplified example.
However, the NSFR does not eliminate the possibility of sudden deposit withdrawals or unexpected disruptions in financial markets.
Its purpose is to discourage excessive reliance on unstable funding arrangements and support a sustainable funding profile.
The LCR and NSFR therefore address complementary dimensions of liquidity risk.
The LCR focuses on short-term stressed cash flows.
The NSFR focuses on structural funding stability.
Neither should be evaluated independently of the institution's actual funding composition and operational readiness.
7. How a Bank Run Develops
A bank run occurs when a large number of depositors or other creditors attempt to withdraw funds within a short period.
The immediate trigger may be concerns about solvency, liquidity, asset values, management quality or the bank's broader financial position.
Bank runs can become self-reinforcing.
When depositors see others withdrawing funds, they may become concerned about whether they will be able to access their own balances.
This encourages additional withdrawals.
Even a bank with substantial assets can encounter serious difficulties if those assets cannot be converted into cash quickly enough.
An Illustrative Scenario
A bank has the following simplified financial position:
| Balance Sheet Item | Amount |
|---|---|
| Cash and reserves | $8 billion |
| Government securities | $32 billion |
| Loans and other assets | $60 billion |
| Total Assets | $100 billion |
| Deposits and other liabilities | $90 billion |
| Accounting equity | $10 billion |
Assume the bank's securities portfolio includes longer-duration instruments that have declined in market value.
The bank may be able to hold those securities and receive contractual payments over time.
However, if depositors demand $25 billion immediately, its $8 billion cash balance will be insufficient.
The institution must obtain another $17 billion through asset sales or borrowing.
If the bank sells securities at a loss, its equity may decline.
If it cannot sell or pledge sufficient assets quickly, payment obligations may remain unmet.
If depositors interpret those difficulties as evidence of financial weakness, additional withdrawals may follow.
In this way, liquidity pressure can contribute to losses and eventually threaten solvency.
8. Silicon Valley Bank: When Liquidity Risk Became Critical
The failure of Silicon Valley Bank in March 2023 is a significant case study in the interaction between interest rate risk, deposit concentration and liquidity management.
The bank had grown rapidly during a period of low interest rates.
It held substantial investments in longer-duration securities and relied heavily on deposits from technology companies and related customers.
As interest rates increased, the market value of many fixed-rate securities declined.
At the same time, the bank's concentrated customer base became more sensitive to deteriorating economic and financial conditions.
How the Crisis Escalated
On March 8, 2023, Silicon Valley Bank announced a balance-sheet restructuring involving securities sales and plans to raise capital.
The announcement contributed to depositor concerns.
On March 9, the bank experienced withdrawals exceeding $40 billion.
Management anticipated approximately $100 billion in additional withdrawal requests the following day.
The bank was closed by California authorities on March 10, 2023.
The Federal Reserve's subsequent review identified serious weaknesses in interest rate risk management, liquidity planning, governance and supervision.
The review also noted that the bank had failed internal liquidity stress tests and lacked workable contingency funding arrangements.
What Made the Failure Important?
Silicon Valley Bank demonstrated that liquidity risk can develop much faster than some conventional risk-management processes anticipate.
Digital banking allowed large customers to transfer funds rapidly.
Depositors were concentrated in interconnected business communities, facilitating swift information sharing.
The institution's financial vulnerabilities became more serious when the market questioned its ability to meet withdrawals without recognizing substantial losses.
Importantly, SVB was not representative of every globally active bank subject to the full Basel III liquidity framework.
Its regulatory requirements reflected the US rules applicable to an institution of its size and category.
The lesson is therefore not that a fully compliant LCR necessarily failed to protect SVB.
Rather, the case demonstrates why capital measures, liquidity planning, interest rate risk management and effective supervision must be assessed together.
9. First Republic Bank: The Limits of Being Well-Capitalized
First Republic Bank provides an especially important example for understanding the limitations of headline capital measures.
The bank had developed a business model serving affluent clients, offering attractive lending terms and relying on relatively low-cost deposits.
Its assets included substantial longer-duration, lower-yielding loans.
When interest rates increased, the economic value of those assets declined relative to prevailing market conditions.
At the same time, the bank's funding structure included a significant concentration of uninsured deposits.
Following the failure of Silicon Valley Bank, depositor confidence weakened and withdrawals accelerated.
First Republic experienced severe liquidity pressure and was closed in May 2023.
The Federal Deposit Insurance Corporation's Office of Inspector General subsequently found that First Republic had been classified as well-capitalized under defined regulatory capital measures during its examination cycles.
Nevertheless, its interest rate exposure, asset-liability mismatch and deposit funding vulnerabilities contributed to its failure.
This distinction is fundamental.
A bank can satisfy regulatory capital classifications while developing liquidity and economic-value vulnerabilities that threaten its survival.
First Republic's experience illustrates why bank analysts must look beyond reported capital ratios to understand funding stability, asset duration and the ability to generate cash under stress.
10. Credit Suisse: Liquidity, Confidence and International Contagion
The crisis involving Credit Suisse in March 2023 provides a different perspective.
Unlike Silicon Valley Bank and First Republic, Credit Suisse was a global systemically important bank operating within a more extensive international prudential framework.
The institution had experienced years of financial, governance and reputational challenges.
Repeated losses, business-model concerns and declining confidence weakened its market position.
During the international banking turmoil of March 2023, pressure on the institution intensified.
Credit Suisse experienced substantial deposit outflows and required extraordinary liquidity support from the Swiss National Bank.
Swiss authorities ultimately facilitated its acquisition by UBS.
Why This Case Matters
Credit Suisse demonstrates that liquidity problems can emerge even at large institutions with extensive regulatory oversight.
A bank's ability to maintain sufficient liquidity depends on more than the absolute amount of liquid assets it holds.
It also depends on whether those resources are accessible, transferable and operationally usable when needed.
Funding confidence and the speed of withdrawals can be decisive.
The Basel Committee's assessment of the 2023 banking turmoil raised questions about the calibration of liquidity assumptions and the practical usability of liquidity buffers during severe stress.
The episode also highlighted how operational liquidity needs and differences between legal entities can complicate an institution's ability to respond.
Credit Suisse's failure should not be reduced to a single weak financial ratio.
It reflected a broader loss of confidence interacting with longstanding institutional weaknesses.
11. Why Rising Interest Rates Can Expose Hidden Vulnerabilities
Interest rates affect both sides of a bank's balance sheet.
When market rates rise, banks may earn more income from floating-rate loans and new investments.
However, they may also face higher deposit costs, reduced bond values and increased funding pressure.
The effect depends on the maturity and repricing characteristics of their assets and liabilities.
The Duration Mismatch Problem
Consider a bank holding substantial long-term fixed-rate securities funded by deposits that customers can withdraw at short notice.
If interest rates rise sharply, the market value of the securities generally declines.
At the same time, depositors may move funds toward higher-yielding alternatives.
The bank may therefore face falling asset market values and increasing funding pressure simultaneously.
This combination can be especially dangerous when a bank depends on concentrated or confidence-sensitive funding.
Unrealized Losses and Liquidity
A bank may not immediately recognize every change in the market value of its securities through net income.
Accounting treatment depends on the classification of those assets and applicable financial reporting standards.
Nevertheless, unrealized losses may become economically important if securities must be sold or pledged during a liquidity crisis.
Selling an asset below its carrying value can turn an unrealized loss into a realized one.
Borrowing against an asset may also be constrained by collateral eligibility, valuation haircuts and available borrowing facilities.
Consequently, reported accounting values and regulatory capital ratios must be considered alongside market valuations and usable liquidity.
12. Why Regulatory Liquidity Ratios Have Limitations
The LCR and NSFR are important improvements in international prudential regulation.
However, they are not designed to predict every possible financial shock.
Their calculations rely on assumptions about cash outflows, funding behavior, asset liquidity and stress conditions.
Actual crises may develop differently.
Deposit Withdrawals Can Accelerate Rapidly
Digital banking allows large depositors to transfer money much faster than was possible during earlier banking crises.
Social media and interconnected professional networks can also accelerate the spread of financial concerns.
The scale and speed of withdrawals observed in 2023 raised questions about whether conventional liquidity assumptions adequately capture extreme bank-run scenarios.
Liquidity May Not Be Immediately Accessible
Some assets may be legally or operationally restricted.
Liquidity held at one subsidiary may not be readily transferable to another.
Certain securities may require time to sell, pledge or transfer.
Operational readiness therefore matters as much as the reported quantity of liquid assets.
Regulatory Ratios Are Snapshots
Reported financial ratios describe a bank's position over specified reporting periods.
They may not fully capture how that position changes during a rapidly developing crisis.
For this reason, banks need more frequent internal monitoring, realistic stress tests and contingency funding plans.
Regulatory ratios are essential safeguards, but they should be treated as part of a broader risk assessment rather than conclusive evidence of safety.
13. A Practical Comparison: Capital Strength Versus Liquidity Strength
Consider two hypothetical banks with similar capital ratios but very different funding structures.
| Financial Indicator | Bank A | Bank B |
|---|---|---|
| CET1 Capital Ratio | 13% | 13% |
| Liquidity Coverage Ratio | 145% | 105% |
| Net Stable Funding Ratio | 120% | 102% |
| Funding Concentration | Diversified | Highly concentrated |
| Reliance on Uninsured Deposits | Relatively low | Relatively high |
| Long-Duration Fixed-Rate Exposure | Moderate | High |
| Contingency Funding Readiness | Well tested | Weak |
Both banks report the same CET1 ratio.
However, Bank B appears more exposed to funding stress.
Its lower liquidity buffers, concentrated deposits and higher duration exposure create vulnerabilities that are not visible from the CET1 ratio alone.
That does not establish that Bank B will fail or that Bank A is completely safe.
The figures are illustrative, and risk depends on many other factors.
Nevertheless, the example demonstrates why comparing banks solely on capital ratios can produce misleading conclusions.
Two banks with identical capital adequacy ratios can have very different capacities to survive a liquidity crisis.
14. How a Liquidity Crisis Can Become a Solvency Crisis
Liquidity problems and solvency problems can reinforce each other.
Suppose a bank faces rapid withdrawals.
It begins selling liquid assets to generate cash.
If market conditions are unfavorable, the bank may realize losses.
Those losses reduce accounting equity and, depending on their nature and regulatory treatment, may reduce regulatory capital.
As the bank's financial condition weakens, depositors and counterparties may become more concerned.
This can accelerate withdrawals and make new funding more expensive or unavailable.
The institution may then need to sell additional assets, potentially creating further losses.
Under sufficiently severe conditions, an initially manageable liquidity problem can contribute to genuine insolvency.
The reverse is also possible.
If borrowers default or assets decline substantially in value, concerns about solvency can trigger withdrawals and a liquidity crisis.
This interaction explains why bank risk management cannot treat capital, funding and asset quality as completely independent concerns.
15. The Role of Central Banks During Liquidity Crises
Central banks can play an important role in supporting financial stability during periods of severe banking stress.
Eligible institutions may be able to obtain central bank liquidity against qualifying collateral under established lending arrangements.
In extraordinary circumstances, authorities may provide emergency liquidity assistance or introduce special measures, subject to applicable laws and institutional arrangements.
Such support can help address temporary liquidity shortages and reduce the risk of disorderly asset sales.
However, central bank liquidity is not a substitute for adequate capital or sound risk management.
Lending against collateral does not eliminate underlying credit losses.
A bank with fundamentally insufficient assets may require recapitalization, restructuring or resolution rather than liquidity support alone.
The availability, pricing, collateral requirements and legal conditions of central bank facilities also differ across jurisdictions.
Banks must therefore understand whether they can actually access such facilities during stress.
Holding eligible collateral is not enough if operational preparations, documentation or legal arrangements are incomplete.
16. Why the International Context Matters
Capital and liquidity regulations are based on internationally agreed principles, but their application differs among jurisdictions.
United States
US banking regulation applies different prudential requirements depending on factors such as institution size, complexity and risk profile.
The 2023 regional bank failures raised significant questions about interest rate risk, liquidity supervision and deposit concentration.
European Union
European banks operate under capital and liquidity frameworks derived substantially from international Basel standards.
Supervisory authorities assess capital adequacy, liquidity, governance and institution-specific vulnerabilities.
However, business models, funding patterns and deposit behavior vary across banks and countries.
United Kingdom
UK prudential supervision emphasizes capital resilience, liquidity adequacy, recovery planning and risk governance.
The framework also considers institution-specific stress scenarios and the ability to manage funding disruptions.
India and Emerging Markets
Banks in India and other emerging economies face similar fundamental risks involving deposit stability, asset-liability mismatches, credit quality and interest rate exposure.
Domestic regulatory requirements may differ from the international Basel baseline.
Banks also operate under different financial market structures and monetary conditions.
In some emerging markets, foreign-currency funding, exchange-rate volatility and cross-border capital flows introduce additional liquidity challenges.
Global Systemically Important Banks
Large internationally active banks may face additional capital and supervisory requirements because their distress could affect the broader financial system.
Their operations across multiple legal entities and jurisdictions also create challenges in moving liquidity between subsidiaries and branches.
A strong consolidated liquidity position does not guarantee that every individual entity has immediate access to the funds it needs.
This makes international liquidity management particularly complex.
17. What Investors and Banking Analysts Should Examine
Banking analysis should combine capital adequacy, liquidity measures, funding composition and economic sensitivity.
| Indicator | What It Reveals |
|---|---|
| CET1 Ratio | High-quality regulatory capital relative to risk-weighted assets |
| Tier 1 Capital Ratio | Broader going-concern regulatory capital strength |
| Total Capital Ratio | Total qualifying regulatory capital relative to risk-weighted assets |
| Leverage Ratio | Capital relative to a broader, non-risk-weighted exposure measure |
| LCR | Short-term liquidity resilience under prescribed stress |
| NSFR | Stability of funding relative to asset and exposure characteristics |
| Uninsured Deposit Concentration | Potential sensitivity of funding to confidence shocks |
| Deposit Concentration | Reliance on a limited set of customers or sectors |
| Unrealized Securities Losses | Potential market-value pressures within investment portfolios |
| Interest Rate Risk in the Banking Book | Sensitivity of earnings and economic value to rate movements |
| Wholesale Funding Dependence | Reliance on market-based borrowing |
| Asset Quality | Potential losses from borrower deterioration |
| Contingency Funding Capacity | Ability to obtain usable liquidity during stress |
These indicators should be considered together.
A bank with strong capital ratios but heavy reliance on volatile funding may remain vulnerable.
Similarly, an institution with large liquidity buffers may face difficulties if those buffers are inaccessible or if the underlying business model is economically unsustainable.
The aim is to understand how the bank behaves under stress rather than simply whether it satisfies regulatory minimums during normal conditions.
18. Building a More Resilient Bank
Strong financial resilience requires an integrated approach to capital, liquidity and risk management.
Diversifying Funding
Banks should avoid excessive dependence on a small number of depositors, industries or wholesale funding providers.
Diversified funding can reduce vulnerability to sudden withdrawals associated with a single customer group.
Managing Interest Rate Risk
Banks should monitor the effects of changing market rates on earnings, securities valuations and the economic value of their balance sheets.
Asset-liability management should incorporate realistic assumptions about deposit behavior and loan repricing.
Maintaining Usable Liquidity
Liquidity buffers must be supported by operational arrangements that allow funds and collateral to be mobilized during stress.
Banks should test their ability to access funding facilities and execute contingency plans.
Conducting Severe Stress Tests
Stress testing should consider scenarios involving rapid deposit outflows, market value losses, reduced access to wholesale funding and unexpected collateral demands.
Institutions should also examine the combined effects of these events rather than assuming they occur independently.
Strengthening Governance
Boards and senior management must understand the institution's funding model, risk exposures and capacity to withstand adverse conditions.
Risk reporting should be timely, accurate and capable of highlighting emerging vulnerabilities.
Strong ratios cannot compensate for ineffective management or weak internal controls.
19. Frequently Asked Questions
Can a bank fail even with a high capital adequacy ratio?
Yes. A bank may satisfy regulatory capital requirements but experience severe liquidity pressure if it cannot meet withdrawals or refinance its obligations. Capital strength alone does not guarantee funding stability.
What is the difference between CET1 and LCR?
CET1 measures high-quality regulatory capital relative to risk-weighted assets. LCR measures eligible high-quality liquid assets relative to modeled net cash outflows over a 30-day stress period.
Is a 100% Liquidity Coverage Ratio sufficient to prevent a bank run?
Not necessarily. It indicates compliance with the prescribed regulatory stress scenario, but actual withdrawals can exceed modeled assumptions or occur more rapidly.
What is the difference between LCR and NSFR?
The LCR focuses on short-term liquidity resilience over 30 days. The NSFR focuses on maintaining a stable funding structure over a one-year horizon.
Can government bonds create liquidity problems?
Yes. Although qualifying sovereign bonds can be high-quality liquid assets, their market values may decline when interest rates rise. Large sales or collateral transactions during stress can crystallize losses or create funding constraints.
Why are uninsured deposits important in banking crises?
Depositors holding balances above applicable insurance limits may be more sensitive to concerns about a bank's financial condition. A concentrated base of large uninsured depositors can increase the speed and scale of withdrawals.
Does central bank emergency lending guarantee that a bank will survive?
No. Central bank lending can help address liquidity shortages, but it does not automatically resolve insolvency, inadequate capital, weak asset quality or broader confidence problems.
Why did the 2023 banking failures matter for Basel III?
The turmoil highlighted issues involving rapid deposit withdrawals, interest rate risk, operational liquidity preparedness and the usability of liquidity buffers. It also raised questions about the scope and calibration of prudential requirements.
Conclusion
Capital adequacy and liquidity are two essential foundations of bank resilience, but neither can be evaluated in isolation.
Capital determines how effectively a bank can absorb losses and maintain financial viability.
Liquidity determines whether it can meet financial obligations when they arise.
A bank may appear adequately capitalized while holding assets that cannot be converted into cash quickly enough to satisfy withdrawals.
It may also hold substantial liquid assets while facing losses that undermine its economic solvency.
The international banking turmoil of 2023 demonstrated how rapidly these vulnerabilities can interact.
Silicon Valley Bank exposed the consequences of concentrated funding, interest rate risk and inadequate contingency planning.
First Republic Bank demonstrated that a bank classified as well-capitalized under regulatory measures can nevertheless face severe liquidity and economic-value pressures.
Credit Suisse illustrated how confidence, institutional weaknesses and operational liquidity constraints can affect a globally important banking institution.
For regulators, banking professionals and investors, the lesson extends beyond any single financial ratio.
Financial resilience requires sufficient capital, stable funding, usable liquidity, effective risk management and credible supervisory oversight.
A strong capital ratio can help a bank absorb losses. Only a resilient balance sheet and reliable liquidity arrangements can help it withstand a sudden loss of confidence.