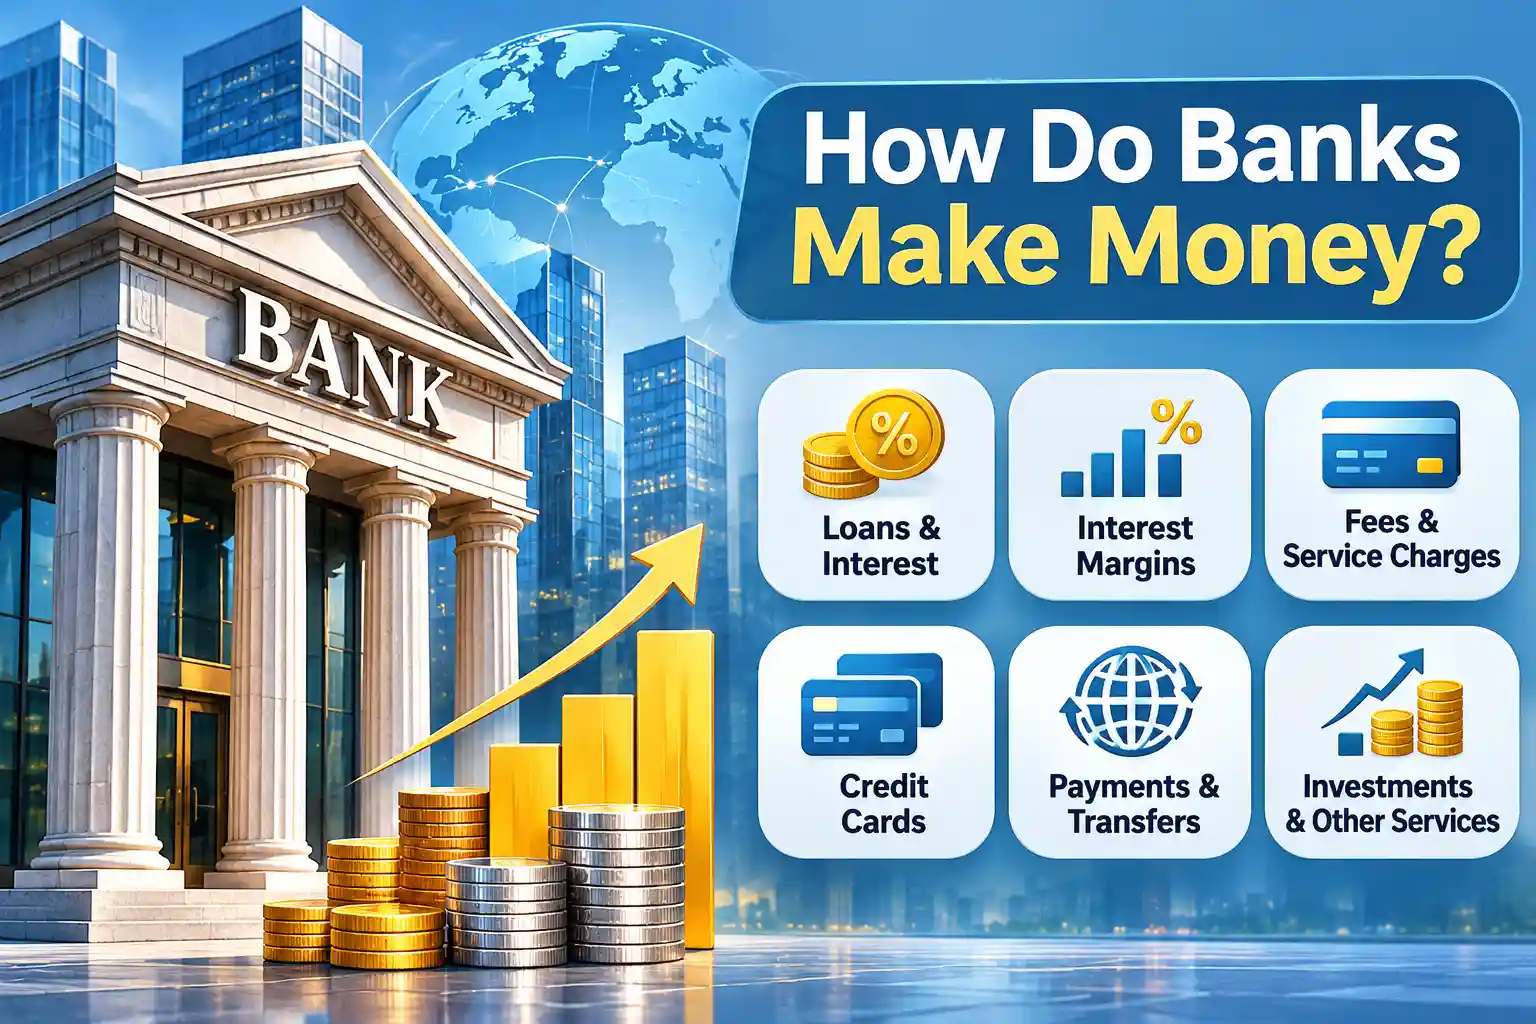
Banks are among the most important businesses in the global economy. They safeguard deposits, provide loans, process payments, and help individuals and companies manage their finances.
But an interesting question remains: How do banks actually make money?
When customers deposit money, banks may pay them interest. When businesses or individuals borrow money, banks charge interest. The difference between the interest banks earn and what they pay to fund their activities is an important source of income.
Yet modern banking is much more complex than simply collecting deposits and issuing loans.
Banks also generate revenue from payment services, transaction fees, foreign exchange, investment activities, wealth management, and corporate financial services.
This guide explains the economics of banking, how banks calculate profits, and why their earnings can change significantly across countries and economic conditions.
1. The Basic Business Model: How Banks Earn Interest
For many commercial banks, lending is one of the largest sources of income.
Banks provide loans to households, businesses, and other borrowers. In return, borrowers pay interest according to the terms of their agreements.
Common lending products include:
- Home mortgages
- Personal loans
- Business loans
- Credit cards
- Vehicle financing
- Commercial real estate loans
- Trade finance facilities
At the same time, banks need funding to support their lending and investment activities.
Customer deposits are one important funding source. Banks may also borrow from other financial institutions or raise money through financial markets.
The difference between interest earned on assets and interest paid on funding is called net interest income.
How Net Interest Income Works
Consider a hypothetical bank with the following annual figures:
| Item | Annual amount |
|---|---|
| Interest earned from loans | $8 million |
| Interest earned from securities and other assets | $2 million |
| Total interest income | $10 million |
| Interest paid on deposits | $3 million |
| Interest paid on other borrowings | $1 million |
| Total interest expense | $4 million |
| Net interest income | $6 million |
The formula is:
Net Interest Income = Interest Income − Interest Expense
In this example:
$10 million − $4 million = $6 million
However, the bank has not necessarily earned $6 million in profit.
It must still account for staff salaries, technology, branches, administration, expected credit losses, taxes, and other expenses.
This distinction is central to understanding banking profitability.
2. Net Interest Margin: An Important Banking Profitability Measure
Banks frequently use Net Interest Margin (NIM) to evaluate the performance of their interest-earning activities.
NIM compares net interest income with the average value of interest-earning assets.
The simplified formula is:
Net Interest Margin = (Net Interest Income ÷ Average Interest-Earning Assets) × 100
For example, suppose a bank reports:
- Annual net interest income: $6 million
- Average interest-earning assets: $150 million
Its net interest margin would be:
($6 million ÷ $150 million) × 100 = 4%
This means the bank generated annual net interest income equivalent to 4% of its average interest-earning assets.
NIM is not the bank's overall profit margin.
It excludes important operating expenses, credit losses, and other components of profitability.
Interest margins differ across institutions and countries because of differences in funding costs, loan types, competition, regulation, and economic conditions.
3. How Banks Make Money From Customer Deposits
Deposits are essential to the business models of many commercial banks.
Customers deposit money in current accounts, checking accounts, savings accounts, and fixed-term deposits.
Banks may pay interest on some accounts, while others pay little or none.
A stable deposit base can be an attractive source of funding.
However, deposits are not simply free money that banks can use without restrictions.
Banks must meet withdrawal obligations, maintain adequate liquidity, manage financial risks, and comply with applicable regulations.
Do Banks Simply Lend Out Depositors' Money?
The familiar explanation that banks take deposited cash and then lend it to somebody else is incomplete.
In modern banking systems, commercial banks can create new deposit money when they issue loans.
For example, when a bank approves a mortgage and credits the borrower's account, it creates a deposit alongside a corresponding loan asset.
This does not mean the bank can create unlimited money or profits.
Banks face capital, liquidity, funding, credit-risk, regulatory, and commercial constraints.
Furthermore, when borrowers transfer funds to customers of other banks, the lending bank may need to settle the payment using reserves or other available liquidity.
Therefore, deposits remain important to banking operations even though lending is not mechanically limited to previously collected deposits.
4. How Banks Earn Money From Fees and Service Charges
Interest is not the only source of bank revenue.
Banks also generate non-interest income by providing financial services.
Depending on the country and institution, these services may include account maintenance, payments, loan origination, financial advice, and account-related facilities.
| Banking service | Potential revenue source |
|---|---|
| Current or checking accounts | Monthly maintenance charges |
| Payment services | Transaction or processing fees |
| International transfers | Transfer fees |
| Loans | Origination or servicing fees |
| Cards | Annual fees and eligible transaction-related revenue |
| Wealth management | Advisory or asset-based fees |
| Business banking | Cash-management and treasury service charges |
Not every bank charges all these fees.
Many financial institutions offer free or discounted services, and certain charges are restricted by consumer protection or banking regulations.
Customers should therefore assess the terms of their individual accounts rather than assuming a universal fee structure.
5. How Banks Make Money From Debit and Credit Cards
Payment cards are another important part of modern banking.
Banks may generate revenue from issuing cards, lending to credit-card customers, and participating in payment transactions.
Credit Card Interest
When cardholders carry eligible unpaid balances, banks may charge interest under their card agreements.
Credit card lending can generate substantial interest income, but it also exposes banks to credit losses.
Annual and Service Fees
Some cards charge annual membership fees, foreign transaction fees, cash-advance fees, or other permitted charges.
Premium card providers may offer rewards and benefits in exchange for annual fees.
Interchange Revenue
In many card payment arrangements, a portion of the transaction economics is allocated to the card-issuing bank through an interchange fee.
The actual arrangement depends on the payment network, card type, transaction, and local regulations.
Interchange revenue should not be confused with the entire merchant service fee paid by a retailer.
Multiple participants, including acquiring institutions, processors, and card networks, may receive portions of payment-related charges.
Why Credit Cards Can Be Risky for Banks
Credit card borrowers may default, dispute transactions, or become unable to repay balances.
Banks must also cover fraud prevention, technology, customer service, rewards, and funding expenses.
High interest rates do not automatically translate into high profits.
6. How Banks Profit From International Transfers and Foreign Exchange
International banking creates additional revenue opportunities.
When customers send money between countries, banks may provide currency conversion and payment services.
For example, a company in Germany might pay a supplier in the United States.
The bank may earn revenue from:
- Foreign exchange conversion margins
- International transfer fees
- Certain payment-processing charges
- Trade finance services
- Foreign currency account services
Understanding the Foreign Exchange Spread
Suppose the reference exchange rate is:
€1 = $1.10
A bank offers a hypothetical customer exchange rate of:
€1 = $1.08
If the customer converts €10,000, the reference-rate equivalent would be $11,000, while the bank's quoted rate would deliver $10,800.
The $200 difference illustrates the potential impact of the quoted exchange rate.
It is not necessarily $200 in net profit for the bank, because currency sourcing, hedging, operational expenses, and other costs may apply.
This is why customers should compare both transfer fees and the actual exchange rate.
For a detailed explanation of international payment infrastructure, see BankingTrail's guides to correspondent banking and SWIFT, SEPA, and ACH.
7. How Banks Earn From Investments and Securities
Banks commonly hold financial assets beyond customer loans.
These may include government securities, high-quality debt instruments, and other permitted investments.
Such investments can provide interest income and support liquidity or balance-sheet management.
Some banks also participate in securities trading and capital-market activities.
Potential sources of revenue include:
- Interest received on bonds
- Securities trading income
- Gains from permitted investments
- Market-making activities
- Investment-related customer services
However, investment activities involve market, interest-rate, liquidity, and counterparty risks.
For example, when market interest rates increase, the market value of existing fixed-rate bonds often declines.
Banks may experience valuation losses even when the underlying bond issuer continues making contractual payments.
The financial impact depends on the accounting treatment, liquidity needs, hedging arrangements, and whether assets are sold.
Therefore, investment portfolios do not provide guaranteed income or guaranteed profitability.
8. Investment Banking and Wealth Management
Not all banks rely mainly on conventional retail lending.
Large international banking groups may operate investment banking, asset management, and wealth management businesses.
Investment Banking
Investment banks and corporate advisory divisions may earn fees for services such as:
- Advising on mergers and acquisitions
- Arranging debt financing
- Underwriting securities offerings
- Helping corporations raise capital
- Providing financial risk-management services
For example, a company seeking to issue bonds may engage an investment bank to structure and distribute the offering.
The bank may receive a fee for its services, subject to the agreed arrangement.
Wealth Management
Banks may provide investment advice, portfolio management, custody, and financial planning services.
They can earn management or advisory fees based on assets, transactions, or agreed service charges.
These businesses may diversify revenue, but earnings can fluctuate with market conditions and customer activity.
9. How Central Bank Interest Rates Affect Bank Profits
Central banks influence financial conditions through monetary policy.
Examples include the US Federal Reserve, European Central Bank, Bank of England, and Bank of Japan.
Changes in policy rates can affect:
- Interest received on new and variable-rate loans
- Interest paid on deposits
- The cost of wholesale borrowing
- Demand for mortgages and business loans
- The market value of securities
- Borrowers' capacity to repay debt
Do Higher Interest Rates Always Benefit Banks?
Not necessarily.
Higher interest rates may initially improve earnings when loan yields rise faster than funding costs.
But customers may demand higher deposit rates, borrowers may reduce borrowing, and some borrowers may face repayment difficulties.
Banks holding longer-term fixed-rate assets can also experience pressure when funding becomes more expensive.
Conversely, lower rates may reduce lending margins but support credit demand and some borrowers' repayment capacity.
The overall effect depends on the institution's business model and balance sheet.
10. How Much Profit Does a Bank Actually Make?
A useful way to understand banking is to examine a simplified income statement.
Consider a hypothetical bank reporting the following annual figures.
| Income statement item | Amount |
|---|---|
| Interest income | $100 million |
| Interest expense | −$40 million |
| Net interest income | $60 million |
| Non-interest income | +$25 million |
| Net revenue | $85 million |
| Operating expenses | −$45 million |
| Credit-loss provisions | −$15 million |
| Profit before tax | $25 million |
| Income tax expense | −$5 million |
| Net profit | $20 million |
Despite generating $125 million in gross interest and non-interest income, this bank earns $20 million in net profit.
The difference reflects the cost of funding, running the institution, and absorbing expected loan losses.
These figures are illustrative and do not represent the financial statements of an actual bank.
11. Why Do Banks Sometimes Lose Money?
Banks can experience losses despite earning substantial revenue.
Loan Defaults
When borrowers cannot repay their loans, banks may need to recognize credit losses.
A deterioration in asset quality can significantly reduce profitability.
Rising Funding Costs
If deposit and borrowing rates increase faster than yields on interest-earning assets, margins may contract.
Market Losses
Changes in interest rates, exchange rates, and security prices may affect the value of financial assets.
Operational Expenses
Banks face costs related to employees, technology, branches, cybersecurity, compliance, and administration.
Fraud and Operational Failures
Fraud, cyber incidents, internal control failures, or payment-system disruptions can create direct losses and additional expenses.
Liquidity Problems
Even a bank with valuable long-term assets may face serious difficulties if it cannot meet short-term payment obligations.
This is why bank profitability, solvency, and liquidity are related but distinct concepts.
12. Do All Banks Make Money the Same Way?
No. Bank revenue models vary significantly.
| Bank type | Typical major revenue sources |
|---|---|
| Retail bank | Consumer lending, deposits, fees, cards |
| Commercial bank | Business lending, trade finance, treasury services |
| Investment bank | Advisory, underwriting, trading and capital-market services |
| Private bank | Wealth management, investment services, specialized lending |
| Digital bank | Lending, payments, subscriptions, account services and partnerships |
| Islamic bank | Sharia-compliant financing, trading, leasing and profit-sharing structures |
These are broad categories, and many institutions operate multiple businesses.
Islamic banks, for example, use financing structures intended to comply with applicable Sharia principles rather than conventional interest-based lending. Their products, accounting treatment, and revenue arrangements vary.
Similarly, a digital bank may operate under a full banking license or through partnerships with licensed institutions, depending on its jurisdiction and structure.
13. Are Banks More Profitable Than Other Businesses?
Banks can earn large absolute profits because they manage substantial volumes of financial assets.
But the size of a bank's net income does not necessarily tell us whether it is unusually profitable.
Financial analysts often evaluate:
Return on Assets (ROA): Net profit relative to average total assets.
Return on Equity (ROE): Net profit relative to shareholders' equity.
Net Interest Margin (NIM): Net interest income relative to average interest-earning assets.
Cost-to-Income Ratio: Operating expenses relative to operating income, calculated using the bank's reported definition.
Nonperforming Loan Ratio: A measure of loans experiencing specified repayment problems relative to the relevant loan portfolio.
These measures provide different perspectives on earnings, operating efficiency, risk, and financial strength.
They should be considered together rather than in isolation.
14. How Do Bank Profits Affect Customers?
Bank profitability influences the financial products and services available to customers.
Banks need sufficient earnings and capital to maintain their infrastructure, invest in technology, manage losses, and support future lending.
However, maximizing bank revenue and maximizing customer benefits are not always the same objective.
Customers may benefit from competition that encourages:
- More attractive savings rates
- Competitive loan pricing
- Lower account and transfer fees
- Improved digital banking services
- Greater payment transparency
- Better customer support
Regulation, market competition, operating efficiency, and customer behavior all affect the balance between banking profitability and consumer interests.
A profitable bank is not automatically the best bank for every customer, just as a bank advertising low fees is not necessarily the safest or most suitable institution.
Frequently Asked Questions
What is the biggest source of income for banks?
For many traditional commercial banks, net interest income is a major revenue source. However, investment banks and diversified banking groups may obtain substantial revenue from fees, trading, and other financial services.
Do banks make money when customers deposit funds?
Customer deposits can provide relatively stable funding that supports a bank's lending and investment activities. Banks may earn income on funded assets, but they also incur expenses and must manage withdrawal obligations.
Do banks earn money from every debit card transaction?
Not necessarily. Revenue allocation depends on card networks, agreements, local regulation, and the transaction structure. Banks may receive interchange income, but not every transaction creates a separate net profit.
Do banks create money when they give loans?
Commercial bank lending commonly creates new deposit money when a loan is issued and the borrower's account is credited. Banks remain constrained by capital requirements, liquidity needs, funding costs, regulation, and credit risk.
Why do banks charge interest on loans?
Loan interest compensates banks for funding costs, credit risk, operating expenses, liquidity considerations, and the use of capital, while also providing an opportunity to earn a return.
Can banks make money without lending?
Yes. Banks may earn revenue from payment services, fees, investments, wealth management, advisory services, and other permitted business activities. However, the business model and legal permissions vary.
Are bank profits guaranteed?
No. Banks face loan defaults, market fluctuations, operating costs, financial crime risks, and liquidity pressures. These can reduce earnings or produce losses.
How do digital banks make money?
Digital banks may use many of the same revenue models as traditional banks, including lending spreads, card-related income, account subscriptions, and payment services. Their cost structures and regulatory arrangements can differ.
Conclusion
Banks make money by providing financial services and managing the relationship between income-generating assets, funding costs, operating expenses, and financial risks.
For many commercial banks, net interest income remains central to the business model. Banks also earn revenue from payments, fees, cards, foreign exchange, investments, and specialized financial services.
However, bank revenue does not equal bank profit.
Loan losses, funding expenses, technology investment, regulation, and economic conditions can all influence financial performance.
Understanding these relationships helps consumers, investors, businesses, and banking professionals better evaluate how financial institutions operate.
Ultimately, a sustainable banking business depends not only on generating income but also on managing risks, maintaining liquidity, protecting customer interests, and remaining financially resilient.
References and Further Reading
- Bank of England — What Do Banks Do?
https://www.bankofengland.co.uk/explainers/what-do-banks-do - Bank of England — Money Creation in the Modern Economy
https://www.bankofengland.co.uk/quarterly-bulletin/2014/q1/money-creation-in-the-modern-economy - International Monetary Fund — Banks: At the Heart of the Matter
https://www.imf.org/en/Publications/fandd/issues/Series/Back-to-Basics/Banks - Federal Reserve Bank of Cleveland — Trends in the Noninterest Income of Banks
https://www.clevelandfed.org/publications/economic-commentary/2019/ec-201914-trends-in-the-noninterest-income-of-banks - Bank for International Settlements — Bank Business Models
https://www.bis.org/publications/bank-business-models - Federal Reserve Bank of St. Louis — Banking Analytics: Lower Asset Yields Squeeze Bank Interest Margins in Q1
https://www.stlouisfed.org/on-the-economy/2026/jun/banking-analytics-lower-asset-yields-squeeze-bank-interest-margins
Disclaimer: This article provides general financial education. Banking regulations, products, profitability measures, and revenue models differ across jurisdictions and financial institutions. Examples are hypothetical unless otherwise stated.